2026Trusted by 11,600+ Malaysian merchants

Credit Card Machine Malaysia: Accept every payment with one smart terminal

Accept Visa, Mastercard, MyDebit, AMEX, UnionPay, DuitNow QR, Touch 'n Go eWallet, GrabPay, Boost, ShopeePay, Alipay and WeChat Pay on one Android terminal. We handle the bank application, installation and training, and our team supports you 24×7 once you're live.

  • No minimum transaction
  • Nationwide installation
  • EPP up to 24 months
Customer tapping a contactless card on an Android smart POS credit card machine at a Malaysian café
11,600+Satisfied merchant clients
16,300+Terminals deployed
300+Payment gateway merchants
8+ yrsServing all 16 states
  • Visa
  • Mastercard
  • MyDebit
  • American Express
  • UnionPay
  • JCB
  • DuitNow QR
  • Touch 'n Go eWallet
  • GrabPay
  • Boost
  • ShopeePay
  • MAE by Maybank
  • Alipay
  • WeChat Pay
  • FPX

Quick answer: how do I get a credit card machine in Malaysia?

To get a credit card machine in Malaysia, you need an SSM-registered business, a bank account in the business name, MyKad copies of all owners or directors, and photos of your premises. A licensed acquirer or authorised provider such as Creditcardmachine.my submits your application to the bank. Approval usually takes 1–6 weeks. Your terminal is then installed and your staff are trained. You pay a Merchant Discount Rate (MDR) on each sale, and the money is credited to your account 1–3 working days after settlement.

1–6 weeksTypical approval time
1–3 daysSettlement to your bank
From RM1No minimum transaction
24×7Merchant support
The fundamentals

What is a credit card machine, and why does your business need one?

A credit card machine is a secure payment device that reads a customer's card, phone or QR code, gets approval from the bank in seconds and confirms the sale. Malaysians also call it a card terminal, EDC machine (Electronic Data Capture), POS terminal or mesin kad kredit.

The single-purpose swipe machines of the past have been replaced by Android smart POS terminals. These rugged, smartphone-like devices have a touchscreen, a built-in thermal printer, 4G and Wi-Fi, NFC for contactless "tap" payments and a battery that lasts a full business day. One device now accepts credit cards, debit cards, DuitNow QR and every major e-wallet, so you no longer need a counter full of QR standees and separate machines.

The shift matters because Malaysian consumers have moved firmly to digital payments. Many customers now carry little or no cash. A business that can't take a card or QR payment loses sales to a competitor that can, often without ever knowing it.

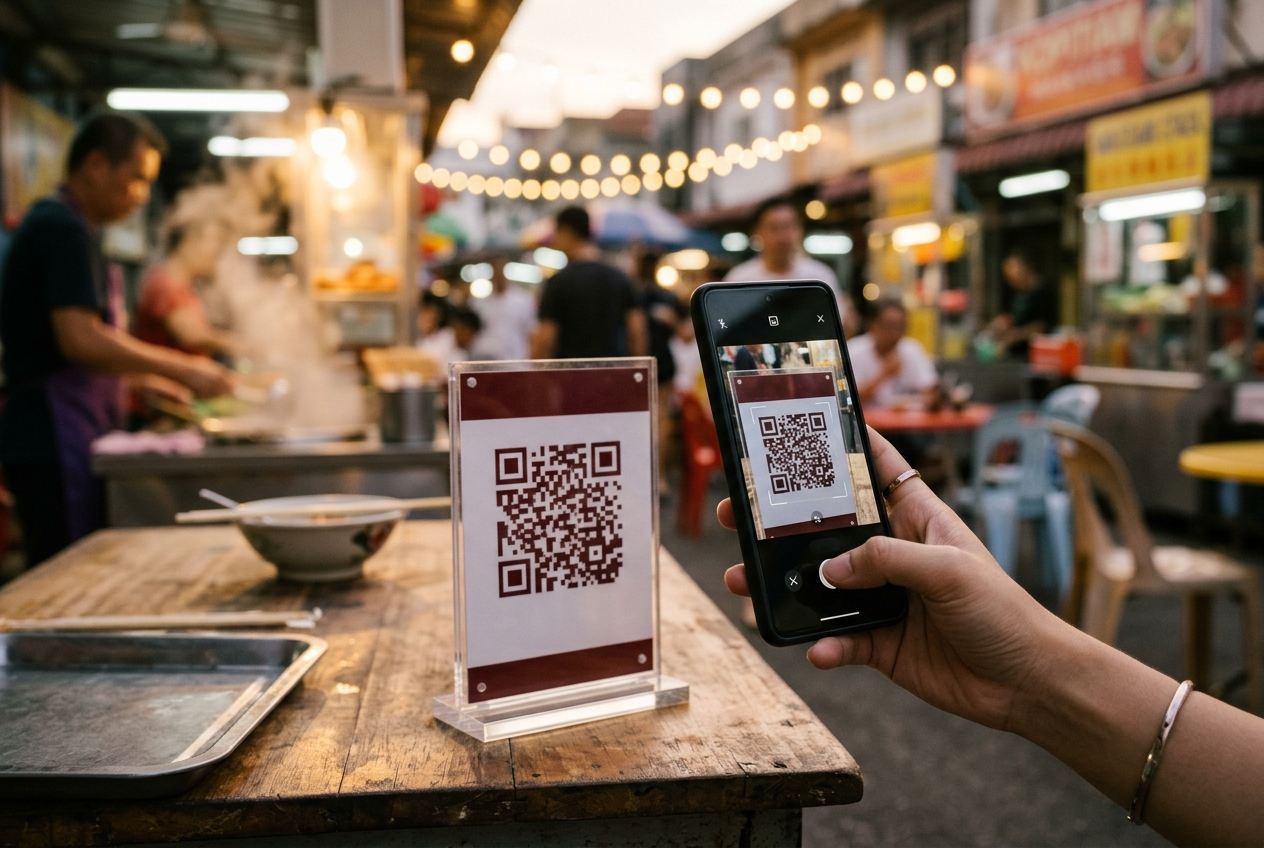
Customer scanning a DuitNow QR code with a smartphone at a Malaysian hawker stall
Even hawker stalls now go cashless, with DuitNow QR and e-wallets on every phone.

What a card terminal does for your business

  • No lost sales. Customers without cash can still buy.
  • Bigger baskets. Shoppers aren't limited to the cash in their wallet, and EPP instalments make high-value purchases possible.
  • Faster checkout. Contactless payments are done in about a second, which shortens queues at peak hours.
  • Less cash risk. You handle fewer notes, so there's less theft, fewer counterfeits and fewer counting errors.
  • Clean records. Every sale is logged for reconciliation, accounting and e-invoicing.
  • Tourist-ready. Accept foreign Visa, Mastercard, UnionPay, Alipay and WeChat Pay.
  • Credibility. Modern payment options tell customers you're an established, professional business.
Solutions

One partner for every way your customers pay

Take payments at the counter, at the table, at the customer's door, online, over the phone or in instalments. We set everything up through Malaysia's leading acquiring banks and card schemes.

Core service

Credit Card Machine & Android Smart POS

Our flagship all-in-one terminal handles chip, contactless and magstripe cards, DuitNow QR and e-wallets. It prints receipts, runs on 4G or Wi-Fi and shows real-time sales reports, all from one handheld device.

  • Approved through Bank Negara Malaysia-regulated acquirers
  • Pay-at-table, queue-busting and on-the-go payments
  • Pre-authorisation, void, refund and daily settlement
  • Installation, staff training and onsite technician support
VisaMastercardMyDebitAMEXUnionPayDuitNow QR

e-Wallets & DuitNow QR

Accept Touch 'n Go, GrabPay, Boost, ShopeePay, MAE, Alipay and WeChat Pay, with local and cross-border QR on the same terminal.

Online Payment Gateway

Take FPX online banking, cards and e-wallets on your website or online store, with secure checkout and integration support.

Payment Links (MG Link)

Send a secure payment link by WhatsApp, SMS or e-mail and get paid from your smartphone, with no terminal needed.

Easy Payment Plan

Offer instalments of up to 24 months on participating credit cards, so high-value sales are easier to close.

Mail Order & Telephone Order (MOTO)

Accept card payments for phone and mail orders, deposits and bookings without the cardholder being present. Payments are keyed in securely by approved merchants, which suits hotels, clinics, event organisers and B2B suppliers.

Prepaid Top-Up & Bills

Earn extra margin and bring in more walk-in customers by offering mobile reloads and utility bill payments at your counter.

Business Internet

We register TM Unifi, Maxis Fibre or TIME for your shop at no registration charge and arrange the installation schedule.

Hardware

Choose the right card terminal for how you sell

The best credit card machine depends on where you take payments, how many transactions you handle and whether you also need point-of-sale features. These are the three main options we supply across Malaysia.

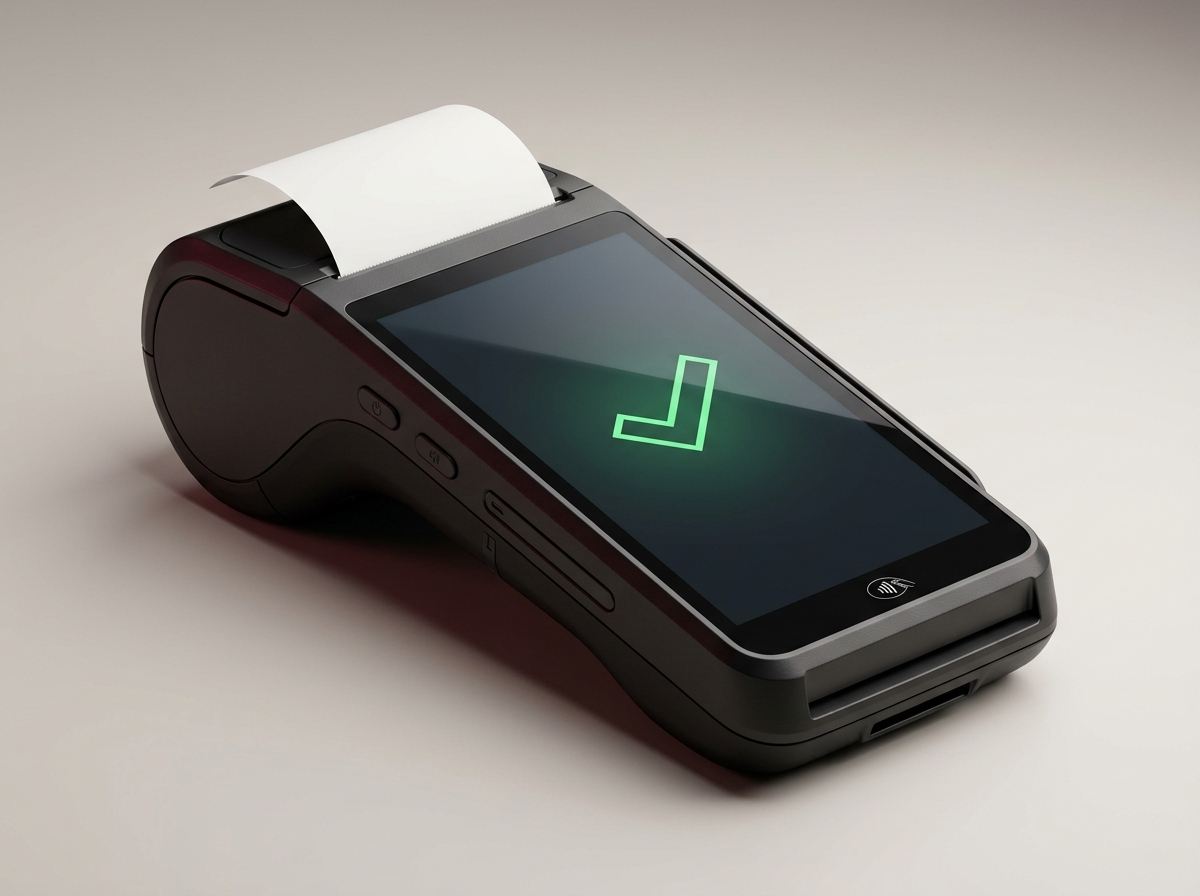
Most popularAndroid smart all-in-one POS terminal with touchscreen and built-in receipt printer

Android Smart All-in-One POS

  • Touchscreen
  • 4G + Wi-Fi
  • Built-in printer
  • NFC · QR

A handheld Android terminal for most SMEs. It accepts every card and QR payment, prints receipts and runs business apps for item lists, sales reports and loyalty programmes. The battery lasts a full trading day.

  • Retail, F&B, clinics, salons, services
  • Pay-at-table and queue-busting
  • Real-time transaction reports
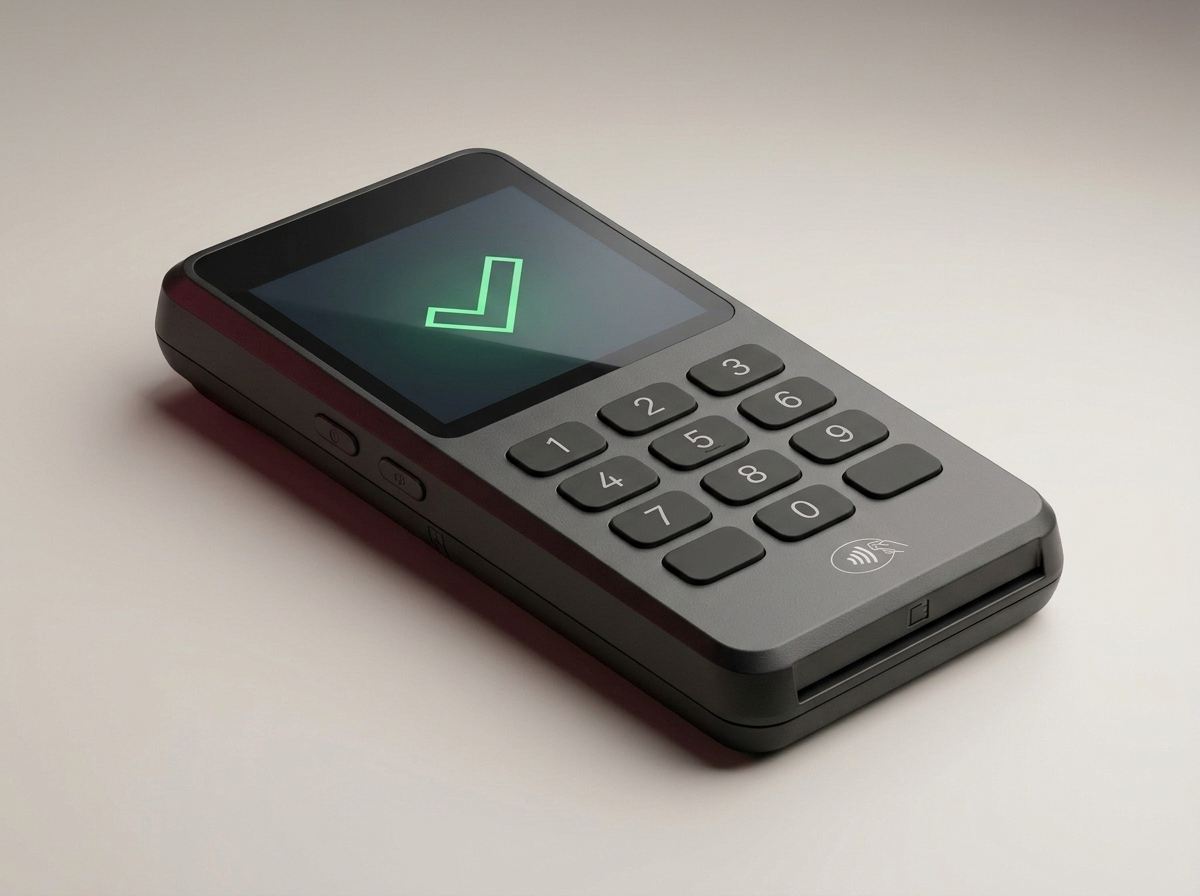
Compact wireless portable card terminal with keypad

Wireless / Portable Terminal

  • 4G mobile data
  • Pocket-sized
  • Long battery

A compact, rugged card machine that works anywhere with phone signal. Use it for deliveries, events, bazaars, home services and anyone who collects payment at the customer's door instead of at a counter.

  • Delivery & cash-on-delivery
  • Events, pop-ups & night markets
  • Mobile technicians & contractors
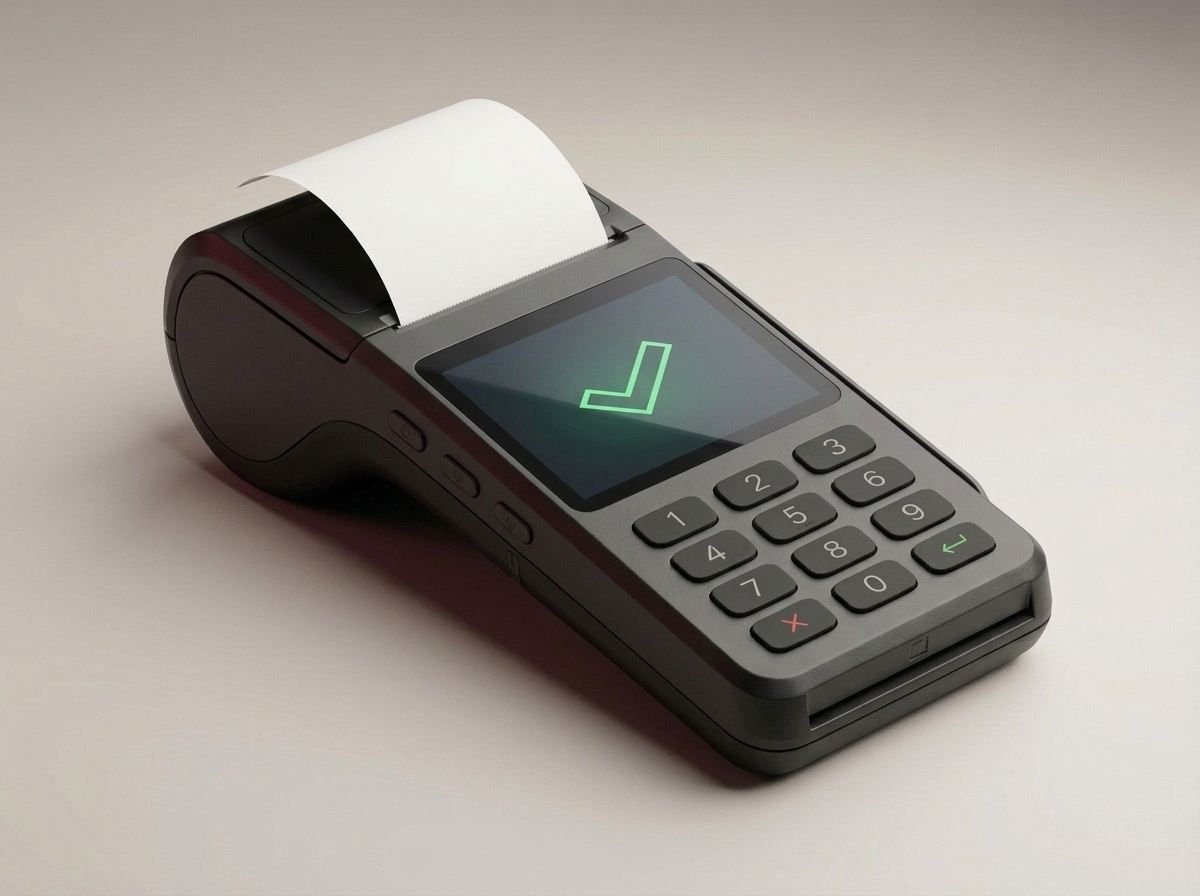
Countertop EDC credit card terminal with keypad and receipt printer

Countertop EDC Terminal

  • LAN / Wi-Fi
  • 4G backup
  • High volume

The classic fixed terminal for busy cashier counters. It is very stable and fast, and works well for supermarkets, pharmacies, hardware stores, petrol kiosks and service centres that process hundreds of transactions a day.

  • Supermarkets & mini-marts
  • Pharmacies & hardware stores
  • Optional customer PIN pad
Credit card machine comparison: Smart POS vs Wireless vs Countertop
FeatureAndroid Smart POSWireless TerminalCountertop EDC
Best forMost SMEs, F&B, retail, clinicsDelivery, events, mobile servicesFixed, high-volume counters
Connectivity4G + Wi-Fi4G / GPRSLAN / Wi-Fi (+ 4G backup)
PortabilityHandheldPocket-sizedFixed
Contactless (NFC)✓ Yes✓ Yes✓ Yes
DuitNow QR & e-wallets✓ On-screen / scannerModel dependentModel dependent
Built-in receipt printer✓ Yes✓ Yes✓ Yes
Business apps & reports✓ AdvancedBasicBasic

Models and specifications depend on the acquiring bank and stock at the time of application. Our consultants will recommend the terminal that fits your business.

How it works

What happens in the three seconds after a customer taps

Every card payment passes through a secure, regulated network. Knowing how it works helps you understand fees, settlement times and security.

  1. Capture

    The customer taps, inserts or swipes a card, or scans a QR code. The terminal encrypts the payment data straight away.

  2. Authorise

    The request goes to your acquirer (merchant bank), through the card scheme (Visa, Mastercard or MyDebit) to the customer's issuing bank.

  3. Approve

    The issuing bank checks the funds and runs fraud checks, then approves the payment. The terminal confirms the sale and prints a receipt.

  4. Settle

    At the end of the day you settle the batch. The acquirer deducts the MDR and pays the rest into your business account within 1–3 working days.

Card schemes we support

Local and international cards, including contactless Visa payWave and Mastercard Contactless.

Visa Mastercard MyDebit American Express UnionPay JCB NETS

QR & e-wallets we support

Malaysia's national QR standard plus the local and cross-border wallets your customers use.

DuitNow QR Touch 'n Go GrabPay Boost ShopeePay MAE Alipay WeChat Pay

Customers can pay with cards issued by Maybank, CIMB, Public Bank, RHB, Hong Leong, AmBank, UOB, Bank Rakyat, OCBC, HSBC, Affin, Bank Islam, Standard Chartered, BSN, Bank Muamalat, Alliance, Agrobank, Al-Rajhi, MBSB, Co-op Bank Pertama, Malaysia's digital banks and international issuers.

Why Creditcardmachine.my

We know what banks look for, and we stay with you after go-live

Applying directly with a bank often means long forms, little guidance and slow replies. As an established merchant acquisition partner based in Bandar Sri Damansara, Kuala Lumpur, we match your business to the right acquirer and terminal, prepare a complete application and follow it through to approval. After that, we remain your support team.

Over eight years, we have helped more than 11,600 merchants and deployed over 16,300 terminals across all 16 states and federal territories. Our clients range from single-outlet hawkers to multi-branch retailers, clinics and hotels.

  • Merchant services through Bank Negara Malaysia-regulated acquirers
  • Licensed with multiple global card schemes
  • Digital application and e-KYC: submit documents by WhatsApp or e-mail
  • Recurring, MOTO and authorised charges for subscription and booking businesses
  • Consultants who speak English, Bahasa Malaysia and Chinese
Creditcardmachine.my payment consultant advising a Malaysian business owner on a card terminal
11,600+merchants onboarded across Malaysia

Application handled

Document checks, submission and bank follow-ups

24×7 support

Phone troubleshooting at any hour

Onsite technicians

Installation, training and replacements

Real-time reporting

Reconciliation and monthly statements

Fraud prevention

Monitoring and merchant guidance

Marketing & loyalty

Joint promotions to drive footfall

Market insight

Malaysia has gone cashless. Is your business keeping up?

Digital payments are now the everyday default for Malaysian consumers. Published Bank Negara Malaysia and PayNet figures for 2025 show the scale of the change.

18B+e-payment transactions in Malaysia in 2025
500+e-payments per person per year, more than one a day
~3BDuitNow QR transactions, roughly doubling year on year
2Bcontactless card transactions, up about 20%

Smaller tickets, more taps

Debit-card transactions are growing almost twice as fast as credit cards, and the average debit ticket keeps falling. Malaysians now tap for a RM12 lunch as readily as for a RM1,200 phone. Card and QR acceptance is no longer only for big-ticket retailers. Kopitiams, hawkers, laundromats and car washes need it too.

Tourists pay the way they do at home

Cross-border QR links with Singapore, Thailand, Indonesia, China and other markets let visitors pay with their home apps. For hotels, malls, attractions and restaurants in KL, Penang, Melaka, Langkawi and Kota Kinabalu, accepting UnionPay, Alipay, WeChat Pay and foreign cards brings in revenue that would otherwise go elsewhere.

Figures are rounded from publicly reported Bank Negara Malaysia and PayNet data for 2025 and are given for context.

Pricing & MDR

How much does a credit card machine cost in Malaysia?

There are two costs to compare: what you pay for the terminal, and the Merchant Discount Rate (MDR) on each sale. Here is how both work, so you can judge any offer properly.

1. The Merchant Discount Rate (MDR)

MDR is a percentage of each card or QR transaction that the acquirer deducts before paying you. It covers the interchange fee paid to the customer's bank, the card scheme fee and the acquirer's processing cost. At 1.5% MDR, for example, a RM100 sale settles as RM98.50.

Malaysia has no single government-fixed MDR. Each acquiring bank prices it based on your industry (merchant category code), expected monthly card volume, average ticket size and the cards your customers use. Bank Negara Malaysia regulates the interchange part of the fee, especially for debit cards. That is why MyDebit and local debit transactions are usually the cheapest to accept.

2. Terminal and set-up charges

Depending on the bank and package, a terminal may come with no rental, a monthly rental, a one-off purchase price or a refundable deposit. Some banks waive rental once your card sales reach a monthly threshold. We explain every charge in writing before you sign.

3. Other costs worth asking about

  • Mobile data SIM charges for 4G terminals
  • Thermal paper rolls for the printer
  • Repair or replacement outside warranty
  • Chargeback handling and early termination conditions
Indicative MDR ranges in the Malaysian market
Payment typeTypical MDR*
Local debit / MyDebit≈ 0.15% – 0.8%
DuitNow QR (bank / e-wallet funded)≈ 0% – 0.5%
Local credit card≈ 1.0% – 1.6%
Premium / corporate credit card≈ 1.5% – 2.0%
Foreign Visa / Mastercard≈ 2.0% – 3.0%
AMEX, JCB, UnionPay, Alipay, WeChat PayQuoted separately

*General market ranges for guidance only, not a quotation. Your rate depends on the acquiring bank, business type and volume.

MDR cost estimator

Move the sliders to estimate your monthly card processing cost.

Monthly feeRM 360
You receiveRM 29,640
Yearly feeRM 4,320

Surcharging is not allowed in Malaysia

Bank Negara Malaysia and card-scheme rules prohibit merchants from adding a surcharge or "card fee" for paying by card or DuitNow QR. Treat MDR as a normal operating cost and build it into your pricing.

How to apply

Get your credit card machine in five simple steps

A dedicated consultant guides you from your first message to your first approved transaction. You won't have to chase the bank yourself.

  1. Talk to us

    Call or WhatsApp 016-385 0232. Tell us your business type, location and expected sales, and we'll recommend a terminal and acquirer.

  2. Send documents

    Share your documents by WhatsApp or e-mail. We check every page for completeness before submitting to the bank.

  3. Get approved

    The bank completes its KYC and risk review. Your Merchant ID (MID) and Terminal ID (TID) are then issued.

  4. Install & train

    We deliver and set up your terminal and train your staff on sales, voids, refunds, settlement and reports.

  5. Start selling

    Run a test transaction and go live. Accept cards, DuitNow QR and e-wallets from day one.

Online payment gateway

Contact us → submit documents → approval → website integration → go live. Accept FPX, cards and e-wallets on your website, with integration support for popular platforms and custom builds.

Payment links (MG Link)

Contact us → submit documents → approval → profile creation → start sending links. The fastest way for social sellers and service providers without a counter to accept digital payments.

Document checklist

Documents required to apply for a credit card machine

Every merchant application goes through Know-Your-Customer (KYC) checks required by Bank Negara Malaysia. Choose your business type below and prepare these documents to avoid delays.

Sole proprietorship & partnership

  • SSM Business Registration (Form B & D, or the current SSM business profile)
  • MyKad or passport copies of all owners / partners (front and back)
  • Latest month bank statement showing bank name, account name and account number
  • Premises photos: signboard, interior, product display and equipment

Optional, but speeds up approval

  • Local council / trading / business licence
  • Company invoices, price list or catalogue
  • Tenancy or S&P agreement

How to get approved faster

  • Use a bank account in the exact business name on your SSM registration.
  • Send clear, uncropped photos that show a visible signboard and a trading premises.
  • Give a realistic estimate of monthly card sales and average transaction value.
  • Keep your address the same across SSM, the bank and the application.
  • Reply quickly to any follow-up questions from the bank's risk team.

Common reasons applications stall

  • Name mismatch between the bank account and SSM records
  • Signboard issues, such as a sign still showing a previous owner's name
  • Expired or unreadable MyKad copies
  • Outdated company forms, such as a missing Section 58 or an old director list
  • Higher-risk categories that need more checks, such as some travel, direct-selling or online-only models

We check every file before submission. If one bank declines, we can often place you with another acquirer whose risk appetite fits your business.

Industries

Built for every kind of Malaysian business

From a one-person bazaar stall to multi-outlet chains, we configure the right terminal and features for your trade.

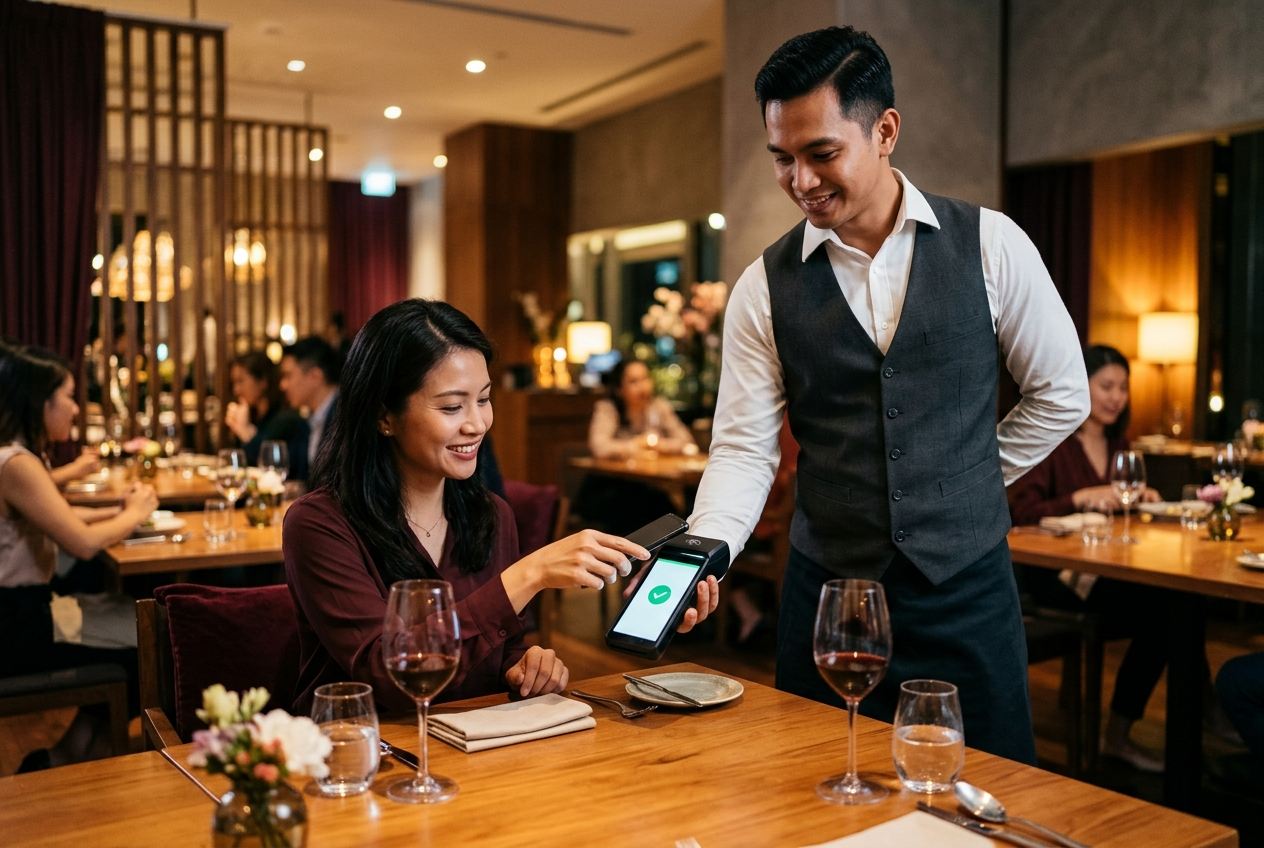
Waiter offering pay-at-table with a handheld card terminal in a Malaysian restaurant
F&B Pay-at-table, faster table turns
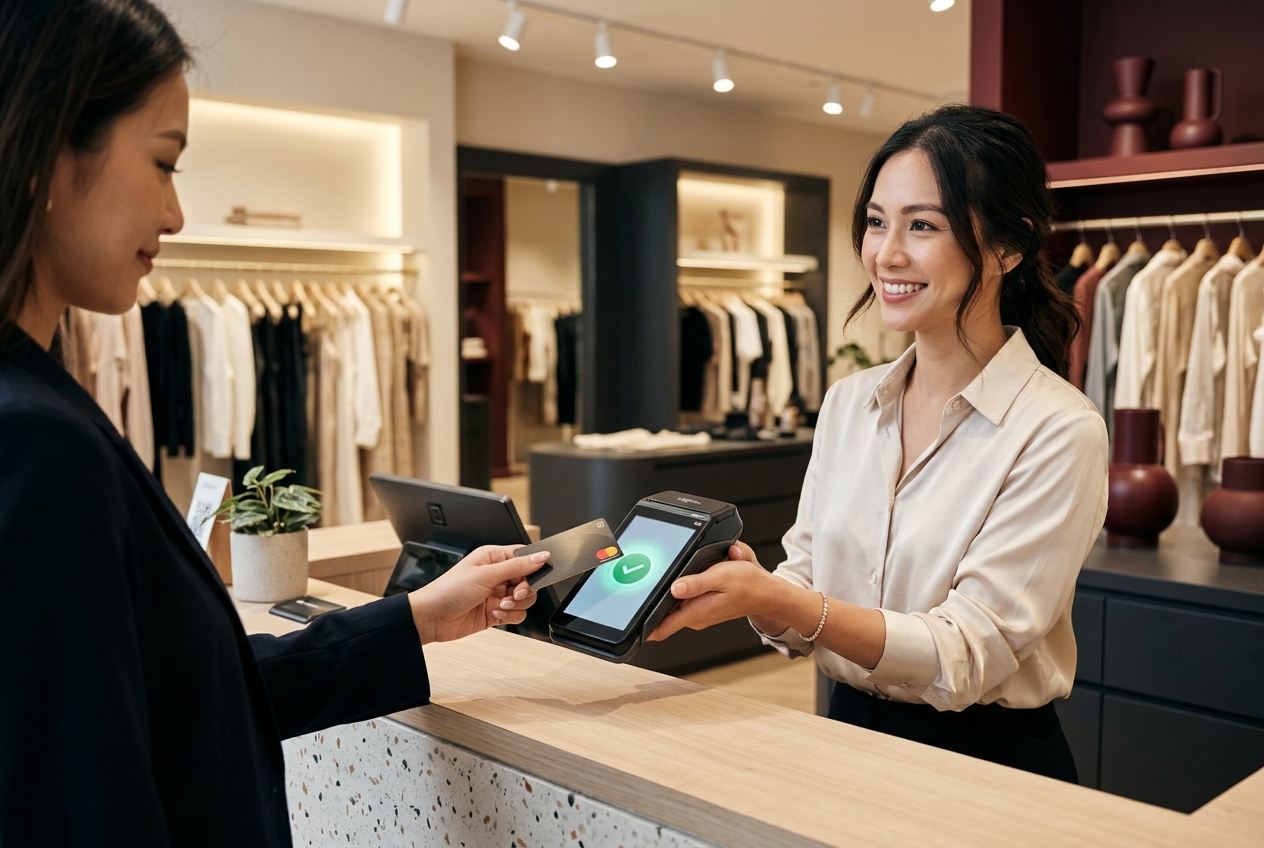
Boutique owner accepting a contactless card payment on a smart POS terminal
Retail Every card and wallet accepted
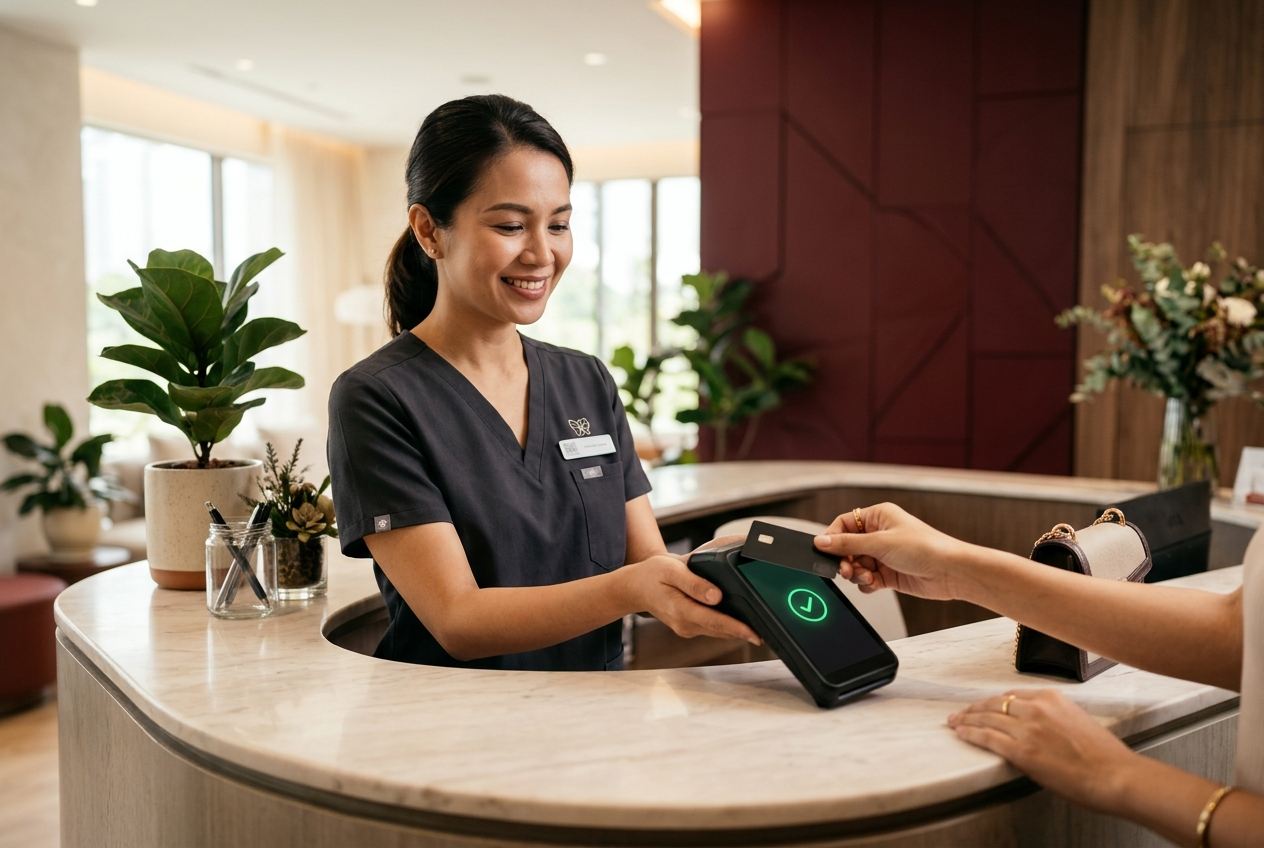
Clinic receptionist accepting card payment on a payment terminal
Healthcare Secure payments and instalments
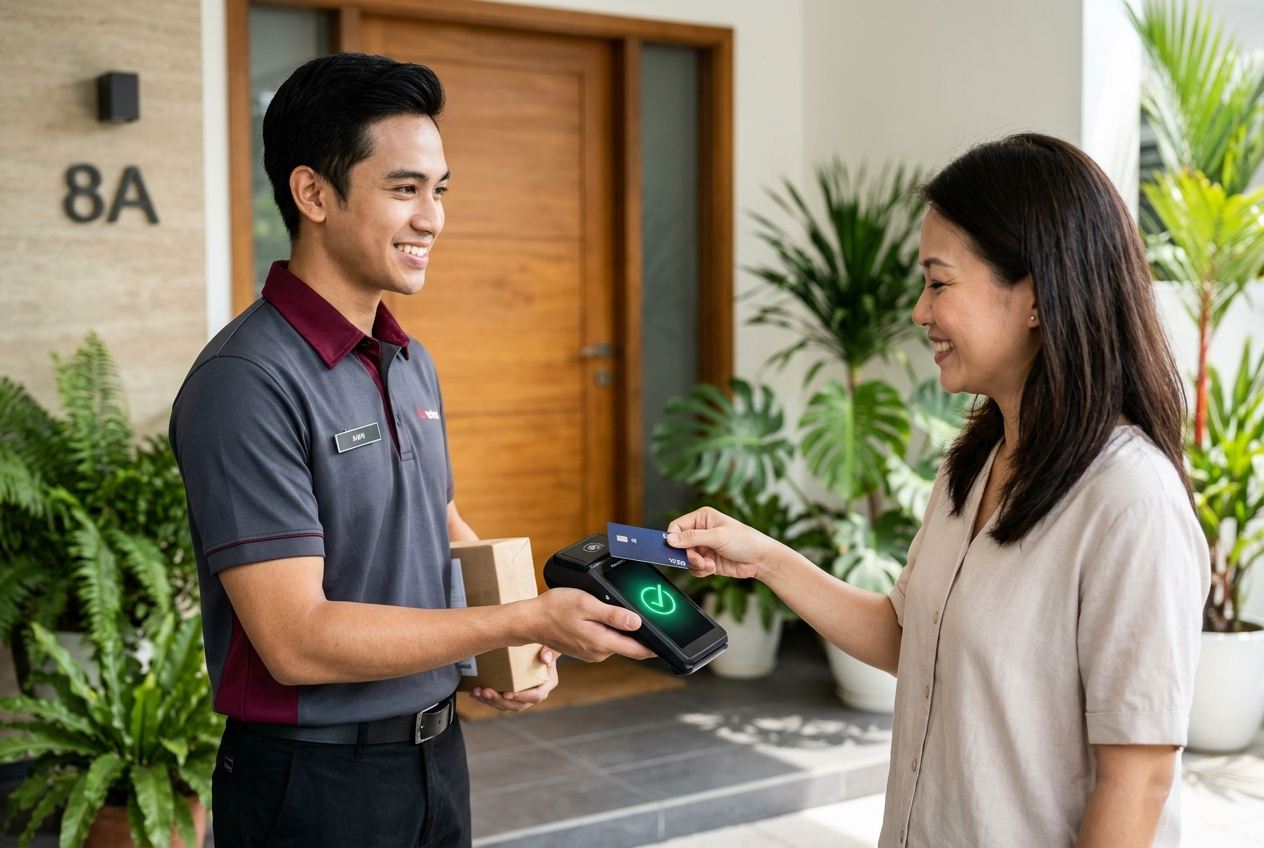
Delivery courier collecting a contactless card payment at the doorstep with a portable terminal
Delivery Get paid at the door on 4G

Restaurants, cafés & kopitiams

Pay-at-table to turn tables faster, shorter counter queues, and 4G terminals for food trucks and night markets.

Retail & boutiques

Fashion, electronics, furniture, jewellery, mini-marts and pharmacies. Accept every card and offer EPP on big-ticket items.

Clinics & healthcare

GP, dental, aesthetic, physio and veterinary practices. Secure consultation payments and instalments for treatments.

Salons, spas & fitness

Sell memberships and prepaid packages, and secure booking deposits with MOTO or payment links to cut no-shows.

Hotels & tourism

Accept foreign cards, UnionPay, Alipay and WeChat Pay. Handle pre-authorisations, deposits and tour bookings.

Automotive & workshops

Service centres, tyre shops, car wash and dealers. Large repair bills are easier to pay by card or instalment.

Delivery & mobile services

Collect payment at the doorstep: aircon servicing, pest control, movers, florists and caterers.

Education & professional

Tuition centres, kindergartens, consultants and firms. Collect fees by terminal, link or recurring charge.

Online & social commerce

Sell on your website, Instagram, TikTok or WhatsApp, and accept FPX, cards and e-wallets without a shopfront.

Merchant reviews

Trusted by business owners across Malaysia

What merchants say about our terminals, our service and our people.

★★★★★
"Very useful credit card and e-wallet terminal. It's portable and we can bring it out everywhere, with no Wi-Fi connection needed. The payment link service is great too: customers pay through the link without walking into our shop, which saves time for both of us. Highly recommended."
ELService business ownerVerified merchant review
★★★★★
"Machine is good to use, I can take it everywhere to collect payments from my customers. Cyndee is very helpful, explained everything in detail and replies fast. Five-star service."
ALRetail merchantVerified merchant review
★★★★★
"Very good service and fast response. They answered all my questions effectively. Customers can pay by card and e-wallet, and the terminal is very user friendly."
YSShop ownerVerified merchant review
★★★★★
"Great service, and the credit card machine is easy to use. They kept me informed with updates the whole time. Well deserved. Good job, Cyndee and team."
BOBusiness ownerVerified merchant review
★★★★★
"Very friendly, and gave us all the guidelines and updates from the beginning until now. Highly recommended."
KCF&B operatorVerified merchant review
★★★★★
"Good service, prompt action. The terminal is very easy to use. Highly recommended."
CKAutomotive workshopVerified merchant review
Case studies

Real payment problems, solved

How Malaysian merchants use our all-in-one wireless touchscreen terminal (card and e-wallet acceptance) to grow and work more efficiently.

Automotive
+15–20%sales uplift

Customers chose the shop that accepts cards

An engine oil and car servicing shop noticed that customers actively look for merchants that accept cards and e-wallets, so they can spread payments and keep cash for other needs.

Solution
All-in-one wireless terminal accepting cards and QR e-wallets
Result
Sales increased by at least 15–20%
F&B
0counter queues at peak

From dial-up machine to pay-at-table

A busy restaurant still used an old wired dial-up card machine, so diners queued at the counter during lunch and dinner. Staff time went into managing the line instead of serving tables.

Solution
Wireless smart terminal that waiters bring to the table
Result
Faster table turns and a better guest experience
Business takeover
Fastapproval after rejection

Approved where another provider failed

A new owner who had just taken over a business was turned down by another provider. The signboard still showed the previous management and some documents weren't ready.

Solution
Guided document preparation and a better-matched acquirer
Result
All-in-one touchscreen terminal deployed quickly
Multi-outlet retail
Secondsper transaction

No more declined cards or dropped connections

A merchant's previous terminal couldn't accept some bank cards and often lost connection. Their other outlet already used our terminal, so they knew the difference.

Solution
Rapid replacement with our 4G + Wi-Fi smart terminal
Result
"Very user friendly and very fast"
Hair salon
RM100+average bill

Selling premium packages with confidence

A barbershop whose customers regularly spend over RM100, and buy colouring and treatment packages, needed a smoother way to accept larger payments.

Solution
Card and e-wallet terminal with instalment options
Result
Easier upselling and more convenient checkout
Restaurant
RM1.50–150ticket range

Every generation pays their way

A family restaurant found that younger diners prefer e-wallets while older diners prefer cards. Asking customers to use a method they don't like was costing goodwill.

Solution
One terminal accepting the full range of cashless payments
Result
Every customer can pay the way they prefer
Buyer's guide

How to choose the best credit card machine provider

Before you sign with anyone, compare these eight factors. They have the biggest effect on what you pay and how smoothly your payments run.

01 · Total cost

Compare MDR by card type, plus rental, deposits, SIM fees and minimum-volume conditions. A low headline rate can still cost more.

02 · Payment coverage

Make sure MyDebit, DuitNow QR and the main e-wallets are included alongside Visa and Mastercard.

03 · Settlement speed

Funds should arrive within 1–3 working days so your cash flow stays healthy.

04 · Connectivity

4G with Wi-Fi backup keeps you selling when the shop broadband goes down at peak hour.

05 · Local support

Downtime costs money. Insist on 24×7 phone support and onsite technicians.

06 · Growth features

EPP, MOTO, pre-auth, payment links and an online gateway let you grow without switching provider.

07 · Reporting

Real-time and monthly reports make reconciliation, SST and e-invoicing much easier.

08 · Contract terms

Read the lock-in period, termination, replacement and chargeback clauses before you sign.

Three ways to get a card terminal in Malaysia
CriteriaApply directly with a bankCreditcardmachine.myFintech card reader
Application guidanceSelf-service formsDedicated consultant end to endSelf-service online
Choice of acquirerOne bank onlyMatched to the best-fit bankSingle provider
Terminal optionsBank's standard modelSmart POS, wireless or countertopBluetooth reader + phone
e-Wallets & DuitNow QRVaries✓ Broad local + cross-borderUsually
EPP instalmentsBank's own cards✓ Up to 24 monthsRarely
After-sales supportCall centre✓ 24×7 + onsite technicianE-mail / chat
Online gateway & linksSeparate application✓ Same partnerSometimes
Security & compliance

Bank-grade security on every transaction

Every payment carries your customer's financial data and your reputation. Our terminals and acquiring partners meet international and Malaysian security standards.

EMV chip & contactless

Each chip or tap transaction generates a unique cryptogram, so cloned or skimmed card data is practically useless. Malaysia has required PIN for card payments since 2017, and our terminals fully support PIN entry and issuer contactless limits.

PCI PTS & PCI DSS

Terminals are certified to the PCI PIN Transaction Security standard. Card data is encrypted the moment it is read and never stored in readable form. Our acquirers run PCI DSS-compliant processing environments.

Regulated by BNM

Merchant acquiring in Malaysia is regulated by Bank Negara Malaysia under the Financial Services Act 2013. We work only with BNM-regulated acquirers and licensed card schemes, with clear rules on surcharging and disputes.

Fraud prevention checklist for merchants

  • Keep the customer's card in their sight. Bring the terminal to them, especially at tables.
  • Never key in card numbers by hand unless you are an approved MOTO merchant.
  • Be careful with unusually large first orders that ask for delivery to a different address.
  • Never split one sale across several cards to get around a decline.
  • Check the terminal daily for signs of tampering and report anything unusual immediately.
  • Settle daily and keep receipts and delivery proof for at least 18 months.

Chargebacks, explained simply

A chargeback happens when a cardholder disputes a transaction with their bank, for example because they don't recognise it or the goods never arrived. The acquirer will ask you for evidence such as signed receipts, invoices and delivery records. Good records and a clear refund policy are your best protection.

e-Invoicing readiness

LHDN (HASiL) is rolling out its MyInvois e-Invoice system in phases based on annual turnover. Terminal reports give you an accurate daily record of every electronic sale, which makes consolidated e-invoices and month-end reconciliation easier. Check hasil.gov.my for the timeline and thresholds that apply to your business.

Merchant insights

Guides to help you get more from cashless payments

Practical, plain-language guidance from our payment consultants.

Guide4 min read

Contactless payments: how "tap to pay" really works

Contactless payment uses Near-Field Communication (NFC), a short-range radio technology that works within a few centimetres. When a customer holds a card, phone or smartwatch near the terminal, the two devices exchange an encrypted, one-time code instead of the real card number.

Read the full guide

Why it's faster

No swiping, no signing and, for smaller amounts, often no PIN. The transaction finishes in about a second, so queues move faster at busy times.

Why it's safer

Each tap creates a unique cryptogram, so intercepted data can't be reused. With mobile wallets such as Apple Pay, Google Pay and Samsung Pay, the real card number is replaced by a device token and confirmed by fingerprint or face recognition.

What merchants need

An NFC-enabled terminal, which all our current models include, and a visible contactless symbol at the counter so customers know they can tap.

Strategy5 min read

Credit, debit or QR: what Malaysian customers prefer

Different customers pay differently, and the busiest merchants accept all of them. Younger customers usually reach for DuitNow QR or an e-wallet. Working professionals tap a debit or credit card. Tourists use foreign cards, UnionPay, Alipay or WeChat Pay.

Read the full guide

Debit cards for everyday spending

Debit is the fastest-growing card type in Malaysia, with average ticket sizes falling as customers tap for small daily purchases. For merchants, MyDebit is also among the cheapest methods to accept.

Credit cards for bigger purchases

Customers prefer credit for higher-value items, to earn rewards or to use instalment plans. Accepting credit, and offering EPP, can noticeably raise your average order value.

QR for speed and low cost

DuitNow QR works with every participating bank and e-wallet app, has very low merchant fees and suits low-value, high-frequency sales.

Checklist3 min read

Five signs it's time to upgrade your card terminal

Older terminals cost more than you think: lost sales, slow queues and frustrated staff. If any of these sound familiar, it's time to move to an Android smart POS.

Read the full checklist
  1. It still uses a phone line or LAN only, so you can't take it to the table or the customer's door.
  2. Some cards are declined or it doesn't support DuitNow QR and e-wallets.
  3. Connections drop at peak hours, leaving customers waiting or walking away.
  4. You need separate QR standees and reconcile several reports by hand.
  5. Support is slow, and a breakdown means days without card sales.

A modern smart terminal fixes all five, and switching is usually simpler than merchants expect.

Nationwide coverage

Credit card machine service in every Malaysian state

Headquartered in Bandar Sri Damansara, Kuala Lumpur, we serve merchants in all 16 states and federal territories, from Perlis to Sabah.

  • Kuala LumpurBukit Bintang, Cheras, Kepong, Sri Damansara, Bangsar
  • SelangorPetaling Jaya, Shah Alam, Subang, Klang, Puchong, Kajang
  • Pulau PinangGeorge Town, Bayan Lepas, Butterworth, Bukit Mertajam
  • JohorJohor Bahru, Iskandar Puteri, Batu Pahat, Muar, Kluang
  • PerakIpoh, Taiping, Teluk Intan, Sitiawan, Kampar
  • Negeri SembilanSeremban, Nilai, Port Dickson
  • MelakaMelaka City, Ayer Keroh, Alor Gajah
  • PahangKuantan, Temerloh, Bentong, Cameron Highlands
  • KedahAlor Setar, Sungai Petani, Kulim, Langkawi
  • KelantanKota Bharu, Pasir Mas, Tanah Merah
  • TerengganuKuala Terengganu, Kemaman, Dungun
  • PerlisKangar, Arau, Padang Besar
  • SabahKota Kinabalu, Sandakan, Tawau, Lahad Datu
  • SarawakKuching, Miri, Sibu, Bintulu
  • PutrajayaAll precincts
  • LabuanVictoria and surrounding areas
Glossary

Payment terms, explained in plain language

The key terms Malaysian merchants come across when they start accepting cards.

Acquirer
The bank or licensed institution that processes card payments for a merchant and pays the money into the merchant's account.
Issuer
The bank that issued the customer's card. It approves or declines each transaction.
MDR (Merchant Discount Rate)
The percentage fee deducted from each card or QR transaction. It covers interchange, scheme and acquirer fees.
Interchange fee
The part of the MDR paid to the issuing bank. In Malaysia it is regulated by Bank Negara Malaysia.
EDC (Electronic Data Capture)
The traditional banking term for a card terminal that captures and transmits payment data electronically.
Smart POS
An Android payment terminal that combines card acceptance, QR, a printer and business apps in one device.
MyDebit
Malaysia's national debit card scheme, operated by PayNet, and usually the lowest-cost card type to accept.
DuitNow QR
Malaysia's national QR standard. One code accepts payments from all participating bank and e-wallet apps.
MID / TID
Merchant ID and Terminal ID, the unique identifiers given to your business and to each terminal after approval.
Settlement
The end-of-day process that sends your transaction batch to the acquirer so the money can be paid into your account.
EPP (Easy Payment Plan)
An instalment option that lets credit cardholders spread a purchase over monthly payments, typically 6–24 months.
MOTO
Mail Order / Telephone Order: a card-not-present transaction keyed in by an approved merchant.
Pre-authorisation
A temporary hold on a card's available limit, used by hotels and car rentals, that is completed later.
Chargeback
The reversal of a card transaction after the cardholder disputes it with their issuing bank.
NFC / Contactless
Near-Field Communication, which lets customers pay by tapping a card, phone or smartwatch.
PCI DSS
The Payment Card Industry Data Security Standard, the global security standard for anyone handling card data.
FAQ

Credit card machine questions, answered

The questions Malaysian business owners ask us most. Can't find yours? Our consultants reply within minutes during business hours.

Ask on WhatsApp
How do I apply for a credit card machine in Malaysia?

Call or WhatsApp Creditcardmachine.my at 016-385 0232. Then send your SSM registration, MyKad copies of all owners or directors, your latest business bank statement and photos of your premises. We check the documents, submit them to the best-matched acquiring bank, and arrange installation and staff training once you're approved.

How long does credit card machine approval take?

Approval usually takes 1 to 6 weeks. Each bank has its own lead time, and a complete, clear set of documents from the start is the best way to speed things up.

How much does a credit card machine cost in Malaysia?

There are two parts: terminal charges, which may be waived or set as a rental, purchase price or deposit depending on the bank and package, and the Merchant Discount Rate (MDR) on each transaction. As a general guide, local debit cards cost the least, local credit cards are typically around 1.0%–1.6%, and foreign cards cost more. Contact us for an exact quotation.

What is MDR (Merchant Discount Rate)?

MDR is the percentage fee the acquirer deducts from each card or QR transaction before paying you. It covers the issuing bank's interchange fee, the card scheme fee and the acquirer's processing cost. It varies by bank, business type, monthly volume and card mix.

Is there a minimum transaction amount?

No. There is no minimum transaction amount. You can process any amount, even RM1.00.

Can I charge customers extra for paying by card?

No. Bank Negara Malaysia and card-scheme rules prohibit Malaysian merchants from surcharging customers who pay by credit card, debit card or DuitNow QR. MDR should be treated as a normal business expense.

How soon is the money credited to my bank account?

After you settle the terminal, funds are usually deposited into your business bank account within 1 to 3 working days, depending on the acquiring bank's policy.

What documents does a Sdn Bhd company need?

A Sdn Bhd needs the Super Form (Section 14 & 58) or Forms 9, 23, 24 and 49, the M&A or Constitution, MyKad or passport copies of all directors, the latest company bank statement and premises photos. A business licence, price list and tenancy agreement are optional but helpful.

Can a sole proprietor or home-based business get a card terminal?

Yes. SSM-registered sole proprietors and partnerships can apply. Home-based and online businesses can also use payment links or an online payment gateway if they don't need a physical terminal.

Does the terminal accept DuitNow QR and e-wallets?

Yes. Our Android smart POS terminals accept DuitNow QR, Touch 'n Go eWallet, GrabPay, Boost, MAE, ShopeePay, Alipay and WeChat Pay, as well as Visa, Mastercard, MyDebit, AMEX, UnionPay and JCB cards.

Can I offer instalment plans (EPP) to customers?

Yes. You can offer an Easy Payment Plan of up to 24 months, subject to terms. Instalments are usually available to credit cardholders of the bank that provides your terminal. For example, a CIMB-provided terminal offers EPP to CIMB cardholders.

What is the difference between an EDC machine and a POS system?

An EDC machine captures and processes card payments. A POS system also manages items, inventory and sales reports. Android smart POS terminals combine both in one device.

Can I accept card payments without a physical terminal?

Yes. Payment links let you collect payments by WhatsApp, SMS or e-mail. An online payment gateway takes payments on your website, and MOTO lets approved merchants accept card payments for phone and mail orders.

What happens if my terminal has a problem?

Call our 24×7 support line. Most issues are fixed by phone immediately. If needed, we send a technician onsite to check or replace the terminal.

Do you serve businesses outside Kuala Lumpur?

Yes. We serve merchants nationwide, including Selangor, Penang, Johor, Perak, Negeri Sembilan, Melaka, Pahang, Kedah, Kelantan, Terengganu, Perlis, Sabah, Sarawak, Putrajaya and Labuan.

Is it safe to accept card payments?

Yes. Our terminals are EMV and PCI PTS certified and encrypt card data as soon as it is read. Services are provided through Bank Negara Malaysia-regulated acquirers and licensed card schemes.

Start accepting cards, QR and e-wallets this month

Free consultation, no obligation. Talk to a payment specialist today and get a recommendation that fits your business.

Contact

Talk to a payment specialist

Tell us about your business, and we'll recommend the right terminal, acquirer and rate, then handle the application for you.

Request a free consultation

We usually respond within one business hour.

Prefer to talk? Call 016-385 0232. Your details are used only to respond to your enquiry.

Call Now WhatsApp